How To Calculate Annual Percentage Yield On Cd

Hey there, money-savvy friend! Let's grab a coffee and chat about something super useful - calculating Annual Percentage Yield (APY) on CDs. Yeah, I know, it's not as exciting as the latest Netflix series, but stick with me, it's actually pretty cool once you get the hang of it.
First things first, what's APY?
Alright, imagine you're at a bank, and they're offering you a Certificate of Deposit (CD). They say they'll give you a certain interest rate, but here's the thing - that rate might not be what you actually earn in a year. That's where APY comes in. It's like the real deal, the actual interest you'll earn in a year, taking into account how often the interest is compounded.
Now, let's get our hands dirty with the formula!
Don't worry, it's not rocket science. You just need to know a few things: the interest rate (let's call it 'r'), the number of times interest is compounded per year (n), and the time you're going to keep your money in the CD (t, in years).
Must Read
The formula looks like this: APY = (1 + r/n)^(nt) - 1. See, I told you it wasn't that bad!
Let's break it down, shall we?
So, you've got your interest rate (r) as a decimal. For example, if the rate is 5%, r would be 0.05. Then there's n, the number of times the interest is compounded per year. This could be once a year (annually), twice a year (semi-annually), quarterly, monthly, or even daily. The more often it's compounded, the higher your APY.
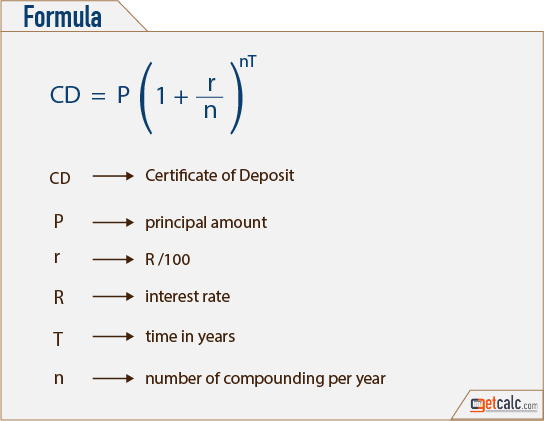
Finally, there's t, the time you're keeping your money in the CD. This could be anywhere from a few months to a few years. Once you've got these three numbers, you can plug them into the formula and voila! You've got your APY.
But wait, there's more!
Let's say you're looking at a CD with an annual interest rate of 5%, compounded semi-annually, and you're planning to keep your money there for 2 years. Plug those numbers into the formula: (1 + 0.05/2)^(2*2) - 1. The result? An APY of about 10.25%. Not bad, huh?
Here's a little tip - if you're comparing CDs, always look for the APY, not just the annual interest rate. It'll give you a much better idea of what you'll actually earn.

Now, let's talk about those sneaky little compounding periods.
You might be thinking, "Wow, compounding more often really boosts my APY!" And you're right, but here's the thing - it can also make the calculation a bit trickier. If the interest is compounded daily, you'll need to know the exact number of days in the year to get an accurate APY. Most banks use 365 days, but some use 360. Just something to keep in mind.
And hey, if you're feeling lazy (or just want to double-check your work), there are plenty of APY calculators online. Just plug in your numbers and let the calculator do the heavy lifting. Easy peasy!

So, why should you care about APY?
Well, my friend, knowing your APY can help you make smarter decisions about your money. It can help you compare different CDs, or even decide if a CD is the right choice for you at all. Plus, it's just good financial hygiene to understand how your money is growing (or not).
And there you have it! You're now a certified APY-calculating pro. Next time you're at the bank, you can impress them with your newfound knowledge. Just don't tell them you learned it all over coffee. They might start inviting you to their meetings.
Until next time, happy calculating!