Fdic Deposit Insurance Standard Coverage Limit 250000 Official

Ever felt like you're living in a real-life episode of "Billions," where you've got so much cash stashed away, you're wondering if it's all insured? Well, fear not, dear reader, because the FDIC, your friendly neighborhood bank babysitter, has got you covered. And no, we're not talking about that '90s sitcom.
Meet Your FDIC Coverage Limit
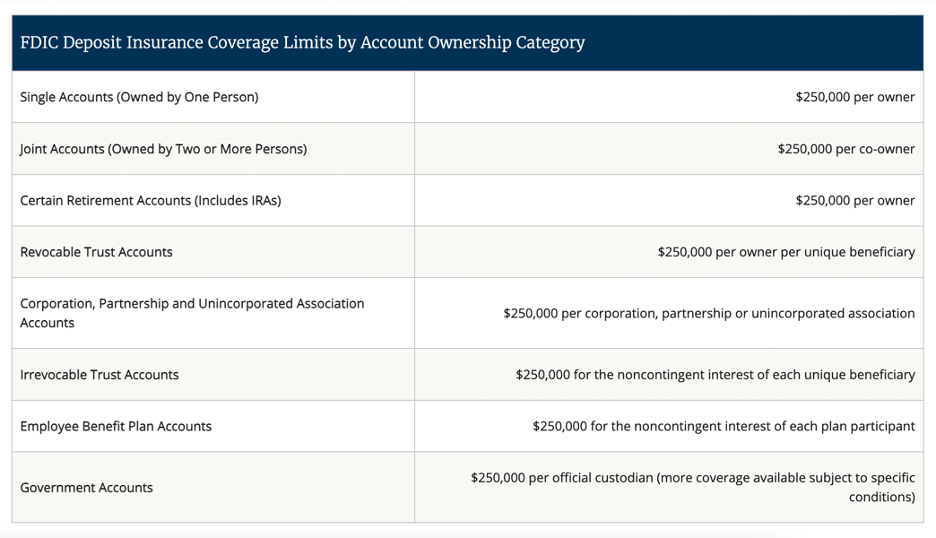
The FDIC, or Federal Deposit Insurance Corporation, is like the ultimate safety net for your hard-earned cash. It's the government agency that protects depositors' funds in case their bank goes belly-up. And guess what? They've just upped their standard coverage limit to a cool $250,000 per depositor, per insured bank, per ownership category.
Now, you might be thinking, "That's all well and good, but what does that even mean?" Well, let's break it down. The FDIC insures deposits up to $250,000 per depositor, per insured bank. So, if you've got your money spread across different banks, you could potentially have up to $250,000 covered at each one. But remember, it's per depositor, not per account.
Must Read
FDIC Insurance: Not Just for Cash
You might be surprised to learn that the FDIC doesn't just cover cash. They insure a whole range of deposits, including checking and savings accounts, money market deposit accounts, and certificates of deposit (CDs). But here's the kicker - they don't insure other financial products like stocks, bonds, mutual funds, or life insurance policies. So, don't go thinking you can stash your Bitcoin in your bank account and expect the FDIC to cover it.
Now, you might be wondering, "How does the FDIC know how much I've got in my bank?" Well, they don't exactly keep tabs on your every transaction. Instead, they rely on periodic bank reports to estimate the amount of insured deposits. But if you're really curious, you can always ask your bank for a calculation of your FDIC-insured deposits.

Maximizing Your FDIC Coverage
So, you've got more than $250,000 in the bank, and you're wondering how to maximize your FDIC coverage? Well, lucky for you, there are a few tricks of the trade.
First up, consider opening different types of accounts. The FDIC insures each ownership category separately, so having a mix of single-ownership accounts, joint accounts, certain retirement accounts, and trust accounts could increase your coverage.
Next, consider spreading your money across different banks. As long as each bank is FDIC-insured, you could potentially have up to $250,000 covered at each one. But remember, it's per depositor, not per account. So, if you've got a joint account with your partner, that's still only $250,000 covered, not $500,000.

And finally, if you're feeling really adventurous, you could consider investing in FDIC-insured certificates of deposit (CDs) offered by banks. These can often provide higher interest rates than traditional savings accounts, but they do come with certain restrictions.
FDIC Insurance: A Brief History
You might be wondering how the FDIC came to be. Well, it all started back in the 1930s during the Great Depression. Banks were failing left and right, and people were panicking, pulling their money out of banks and stuffing it under their mattresses. The FDIC was created in 1933 to restore public confidence in the nation's banking system.
And fun fact for you history buffs out there - the FDIC's official seal features an eagle holding an olive branch in one talon and arrows in the other. It's a symbol of peace and prosperity, and a reminder that the FDIC is there to protect your money, not start a war.
So, What Does This Mean for You?
Well, first and foremost, it means you can sleep a little easier knowing that your money is protected. But it also means that you've got a responsibility to yourself and your family to manage your money wisely. The FDIC is there to provide a safety net, not a get-rich-quick scheme.
So, go ahead, treat yourself to that fancy coffee, or that weekend getaway. But remember to save a little something for a rainy day. After all, as the old saying goes, "Don't put all your eggs in one basket." And with the FDIC, you can make sure that basket is well-insured.