Fdic Standard Maximum Deposit Insurance Amount Official
Alright, picture this: You're at the bank, minding your own business, when suddenly the teller slides a form across the counter and says, "Sign here, please. It's about your FDIC insurance." You squint at the form, then at the teller, and think, "FDIC? Isn't that some sort of secret government agency that insures my deposits? Like a superhero for my money?" Well, buckle up, folks, because we're about to dive into the world of FDIC, its standard maximum deposit insurance amount, and why you should care about it more than your great-aunt Mabel's cat collection.
FDIC: The Unsung Hero of Your Wallet
FDIC stands for Federal Deposit Insurance Corporation. It's like the money version of the National Guard. You hope you'll never need it, but it's nice to know it's there, ready to swoop in and save the day. The FDIC insures deposits up to a certain amount in case your bank goes belly-up. It's like having a financial safety net that catches you when you're doing backflips with your money.
So, What's This Maximum Deposit Insurance Amount, Anyway?
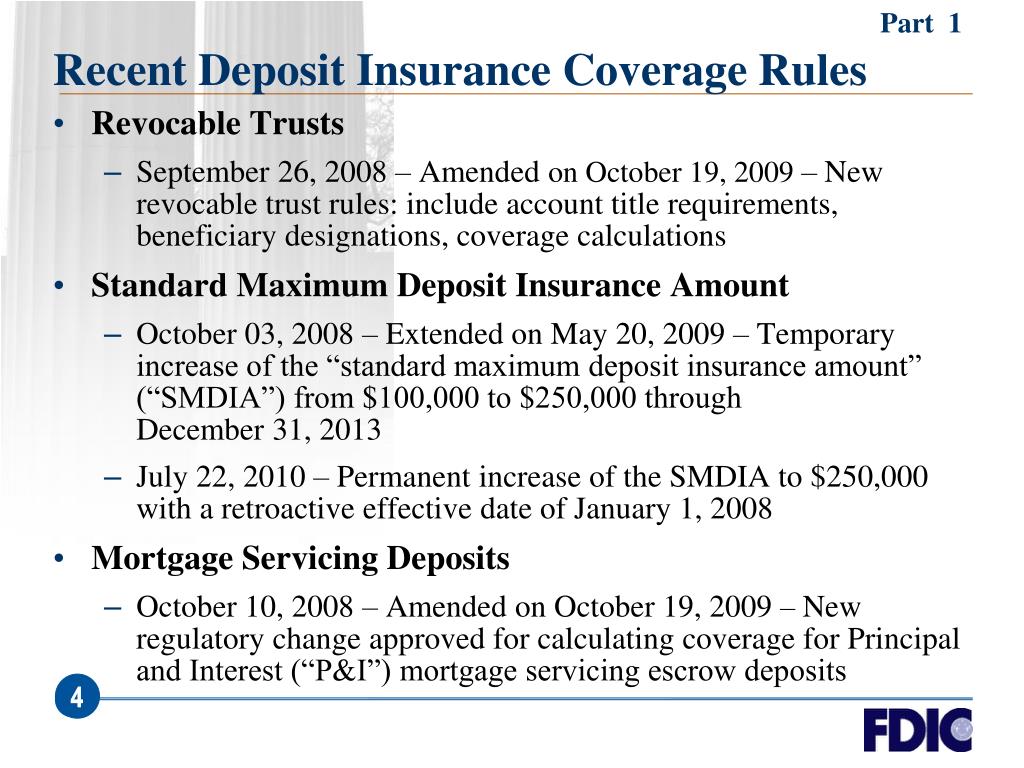
The FDIC standard maximum deposit insurance amount is the most your deposits can be insured for at any one bank. It's like the limit on how much of your money the FDIC will put in its own piggy bank to keep it safe. As of now, that amount is $250,000. That's right, folks. A quarter of a million dollars. More than enough to make Scrooge McDuck do a happy dance.
Must Read
But here's the thing: $250,000 is a lot, but it's not everything. If you've got more than that stashed away, you might want to sit down and have a little chat with your money. Tell it to spread out a bit, maybe open an account at another bank. Because if your bank goes under and you've got more than $250,000, the FDIC won't be able to cover all of it. It'd be like trying to put out a forest fire with a single water balloon.
FDIC Insurance: More Than Just a Number
Now, you might be thinking, "That's all well and good, but I don't have $250,000 just lying around. Why should I care about this FDIC stuff?" Well, let me paint you a picture. Imagine you're walking down the street, minding your own business, when suddenly a giant anvil falls from the sky and lands on your toe. You'd be pretty upset, right? Now imagine that anvil is your life savings, and it's just been squished by a bank failure. That's where the FDIC comes in. It's there to pick up that anvil and say, "Here, have your money back. No harm done."

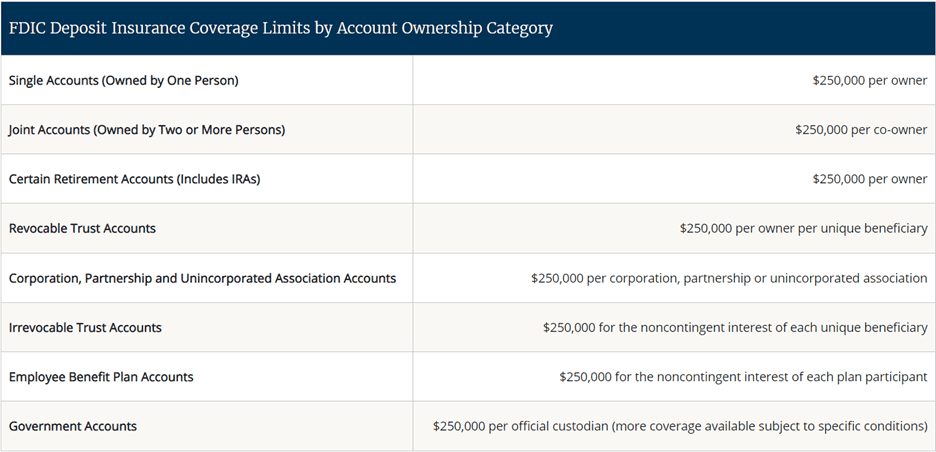
But here's where it gets interesting. The FDIC doesn't just insure your deposits. It insures them per depositor, per insured bank, per ownership category. What does that mean? It means you can have more than $250,000 insured if you play your cards right. For example, if you have a joint account with your spouse, that's $500,000 right there. Add in some retirement accounts, and you could be looking at a cool million. It's like finding out you can order extra cheese on your pizza for free.
FDIC Insurance: The Gift That Keeps on Giving
But wait, there's more! The FDIC also insures certain retirement accounts, like IRAs and Keogh plans, up to $250,000 each. That's right, folks. You can have your regular deposits insured, plus your retirement accounts, and it's all covered under the same FDIC umbrella. It's like having a money raincoat that covers your whole body, not just your head.

And here's a fun fact for you: The FDIC has never missed a payment. Not once. It's like the world's most reliable alarm clock. So, while it's always a good idea to keep an eye on your bank's health (just like you would with a real alarm clock), you can sleep easy knowing that your deposits are in good hands.
FDIC Insurance: The Money-Saving Time Machine
Now, you might be thinking, "This all sounds great, but I don't have $250,000 to deposit right now. What's the point?" Well, let me tell you a little story. Imagine you're walking down the street, and you find a time machine. You hop in, and you're suddenly transported back to the year 2000. You've got a choice: You can either deposit $10,000 in a bank and watch it grow over the next 20 years, or you can leave it under your mattress. What do you do?
If you're smart, you'll take that $10,000 and deposit it in the bank. Because even if you only deposit $10,000, the FDIC will insure it. And if that bank goes under, the FDIC will make sure you get your money back. It's like having a financial time machine that protects your past, present, and future deposits.
FDIC Insurance: The Money-Saving Superpower
So, there you have it, folks. The FDIC standard maximum deposit insurance amount is $250,000, but with a little bit of planning, you can insure even more. It's like having a superpower for your money. It might not seem like a big deal now, but when the giant anvil of bank failure comes crashing down, you'll be glad you had it.
And remember, folks, the FDIC isn't just for the big guys. It's for everyone. Whether you've got $10 in your account or $10,000,000, the FDIC is there to make sure your money is safe. So, go forth, deposit your money, and sleep easy knowing that the FDIC has got your back. And if you ever find a time machine, remember to invest wisely.