Cardinal Glass Industries 401k Principal Loan Rules
When Loans and Glass Collide: A Tale of Cardinal Glass Industries and Your 401(k)
Alright, gather 'round, folks. I've got a tale to spin about Cardinal Glass Industries and their 401(k) principal loan rules. Now, I know what you're thinking, "This sounds about as exciting as watching paint dry." But hold onto your hats, because I'm about to sprinkle some humor and surprise into this financial fiesta.
First Things First: What's a 401(k) Principal Loan?
Imagine you're at a buffet (because who doesn't love a good metaphor involving food?). You've got your plate, and it's piled high with all sorts of delicious retirement savings. Now, a 401(k) principal loan is like when you decide to take a bit of that roast beef before you've paid for it. You're borrowing from your future self, hoping you'll have enough cash to cover the bill when the time comes.
Now, let's dive into the world of Cardinal Glass Industries and their 401(k) loan rules. Remember, these are just the rules for Cardinal Glass employees. If you're not one of them, you might want to skip to the next paragraph. Or not. I won't judge.
Must Read
Cardinal Glass Industries: The Glass Ceiling of 401(k) Loans
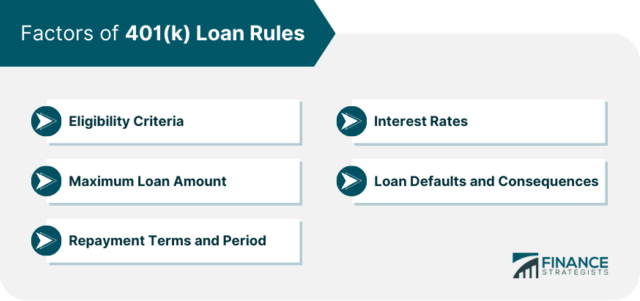
Alright, so Cardinal Glass Industries has a 401(k) plan, and they're nice enough to let you borrow from it. But here's where it gets interesting (or as interesting as 401(k) rules can get). They've got a limit on how much you can borrow. It's like they're saying, "Sure, you can have some of that delicious retirement roast beef, but not the whole dang cow!"
The limit is the lesser of $50,000 or 50% of your vested account balance. Now, I don't know about you, but I've never had $50,000 just lying around. Have you? No? Me neither. So, let's break it down.
If you've got $100,000 in your account, you can borrow up to $50,000. But if you've only got $40,000, you're stuck with a $20,000 loan. It's like they're saying, "Sorry, buddy, you're just not rich enough to borrow more money."
Repaying the Loan: When the Bill Comes Due
Now, here's where things get real. You've got to pay back that loan. And not with IOUs or promises to do the dishes. No, no, no. You've got to use cold, hard cash. The interest rate is pretty reasonable, though. It's the prime rate plus 1%. So, it's not like they're charging you an arm and a leg. Just a finger, maybe.

The repayment period is usually five years. But if you're using the loan to buy a home (because who doesn't love a good real estate metaphor?), you can get up to ten years. It's like they're saying, "Sure, we'll give you extra time to pay back the money you borrowed from your future self. But only if you're buying a house. Because, priorities."
What Happens if You Can't Pay Back the Loan?
Alright, let's talk about the elephant in the room. What happens if you can't pay back the loan? Well, my friends, it's not pretty. The unpaid balance gets considered a distribution. And that means taxes and penalties. It's like they're saying, "You wanted to borrow money from your future self? Well, now you're going to pay taxes on it. And penalties. Lots of penalties."

But here's where it gets surprising (yes, I said surprising in a 401(k) article. Deal with it.). If you get fired, laid off, or retire (because who doesn't love a good retirement metaphor?), you've got until the due date of your tax return to pay back the loan. It's like they're saying, "You lost your job? No problem! Just pay us back by next April 15th. We're not monsters."
So, Should You Take a 401(k) Loan?
Well, that's the million-dollar question, isn't it? The truth is, it depends. If you're in a real bind and you've exhausted all other options, a 401(k) loan can be a lifesaver. But remember, you're borrowing from your future self. And your future self is probably going to want that money for retirement. So, think carefully before you take the plunge.
And there you have it, folks. The tale of Cardinal Glass Industries and their 401(k) principal loan rules. Wasn't that more exciting than watching paint dry? I thought so. Now, who's ready for some real excitement? Like watching grass grow. Or paint dry. You know, the good stuff.